
Genworth bought by China Oceanwide – Sign $2.7B Acquisition Deal
“Genworth Financial, Inc. GNW recently announced that it has inked a definitive agreement with China Oceanwide Holdings Group Co., Ltd. to be acquired by the latter for $2.7 billion or $5.43 per share in cash. The transaction will be executed via Asia Pacific Global Capital Co. Ltd., one of China Oceanwide’s investment platforms. The deal is expected to culminate by the middle of 2017 upon fulfillment of closing conditions.”
See the full Yahoo article here.
GNW Recently Announced. “Genworth and China Oceanwide Sign $2.7B Acquisition Deal.” Genworth and China Oceanwide Sign $2.7B Acquisition Deal. Yahoo! Finance, 24 Oct. 2016. Web. 27 Oct. 2016.
How to Overcome Any Objection
Objections. Some are real. Some are not. The question is: How do you deal with and answer the objection to close the sale? People write books on answering objections, and I don’t have the space here to deal with them all, so let me tell you what I do when the prospect starts throwing out objections.
First, what are the basic objections? No need, no money, no hurry, no confidence. Everything else is a variation of these. Let’s explore:
No need. While many people feel they don’t need life insurance, they do need what life insurance creates. Money. Certainty. Dignity. Peace of mind. If the client has the time, he or she may be able to earn the cash required. But if they don’t get the time and die too soon, life insurance creates the cash. It’s the only product guaranteed to create the cash when the family or company needs it the most.
No money. “I can’t afford the premium.” If the prospect can’t pay the premium, which is just pennies on the dollar, how can the family or company solve the problem? They will need dollars, and those dollars may cost more than a dollar when taxes and other costs are factored in.
There may be assets that can be liquidated, but at what cost? It is something that you should know before you start a business in Orlando. If a business rival knows the prospect needs to sell an asset, and is interested in buying this asset, he will want to negotiate the lowest price possible, and this may be less than the current market value. With life insurance, the beneficiaries know with certainty what they will be receiving.When it comes to estate planning it is always better to consult attorneys as there are many attorneys help with estate planning.
No hurry. “I would like to wait.” Why? What will change between now and next week? This is what I say to prospects: “I appreciate your wanting to take the time to make an informed decision, but while you are thinking it over, let’s find out if you qualify for the coverage.”
Remind you client that there is a cost for everything, including waiting: “The longer you wait, the more the insurance costs. Let’s at least guarantee your insurability to buy you the time to make this decision.”
Let me share with you a story of a client who almost waited too long. Each year for 10 years I met with my client to do his insurance review. Each year I tried to convince him with the help of lawyers for business start ups, of the wisdom of completing his estate planning and purchasing insurance to provide for estate liquidity with the help of experts in the field like estate planning lawyers based in Phoenix . Each year he said no. Then one day I received a call asking me to meet him at his home to talk about the insurance and also about how to write a will which I had been proposing for the past 10 years. One can see here to get an attorney involved to make things easier.
My first question to him was what had changed to make him reconsider the insurance. He told me he had just been diagnosed with a terminal disease and now realized he needed to complete the planning neglected over the previous years. And now he wants to buy insurance! This is one of the main reasons why hiring a professional lawyer for financial legacy planning is important.
Finding out you are uninsurable does expedite the decision making process. Fortunately, we were able to underwrite a second-to-die policy at a reasonable rate with his wife who was a preferred risk, but he almost waited too long.
No confidence. Sometimes the objection from the client is nothing more than a polite way of saying that he or she has no confidence in your suggestions. Perhaps you didn’t take enough time to properly determine the true problems the prospect was concerned about before you made a sales suggestion. The prospect must be disturbed by a problem before action can be taken. Perhaps your suggestions did not quite fit what the prospect was looking for in a financial solution.
Remember, you must determine your prospects wants, needs and desires, and each of these may require a different solution. It’s your job to ask the disturbing questions to encourage the prospects to discuss what problems are of most concern to them today. Then you can make appropriate recommendations to solve the problems in order of priority. You must earn their trust and confidence by doing what is right for them.
One thing to remember as you go to your next appointment: You can’t sell insurance to people who do not care.
The Conflict Behind the DOL Conflict of Interest Rule (The American College Blog)
U.S. Department of Labor’s Conflict of Interest Rule is a hot and controversial topic in the financial services profession. Since the rule was finalized in April 2016, its reception has been predictably divisive. Already, the first of what will likely be a parade of lawsuits has been filed, aiming to stop, dismantle or delay the rule from taking effect next year. Legal hurdles in place, the industry and consumers alike will know soon enough if the DOL rule has strong enough legs.
However, waiting for the outcome of a challenge before preparing for the implementation of the rule should remind us of the fable of the hardworking ant and the carefree grasshopper. While the ant diligently prepares, the grasshopper spends the summer singing the days away and finds itself unprepared to survive through winter.
Let’s not find ourselves like the grasshopper, outside in the cold, shivering and unprepared come next April’s deadline.
Defining a Fiduciary Duty
The DOL rule expands an existing fiduciary duty to include recommendations concerning retirement assets. This will target IRA account holders, rollovers and those who are acquiring, holding, exchanging or distributing retirement assets. This broad net definition covers just about every working or retired American, from a coffee-shop employee saving $50 weekly into a ROTH IRA, to a small business owner opening her first 401(k) plan, to a corporate officer facing retirement with a few million dollars in a profit sharing plan. All of the above are owed a fiduciary duty of care. A better understanding this fiduciary duty requires a visit to the world of academia.
A fiduciary duty can be illustrated as a relationship between two parties. Writing in the Journal of Financial Economics, authors Jensen and Meckling set up the discussion of principal and agent conflicts in their 1974 publication,”Theory of the firm: Managerial behavior, agency costs and ownership structure.”
According to Jensen and Meckling, a client (young employee, business owner, retiree) is viewed as the principal. The principal has an interest in retirement. It may be accumulation of capital, developing an income strategy, meeting bequest motives, developing an appropriate risk tolerance, or a combination of motives. In financial planning we refer to this interest as helping the client understand and meet his specific goals. The counterpart to a principal is an agent. The agent may be an insurance agent, investment adviser, broker, banker or other financial service professional. The agent also has a set of goals and motivations, such as profit, sustainability, growth and financial success.
The Conflict Over ‘Conflict of Interest’
The principal/agent model has natural conflicts. An agent has a set of best interests (success and profit) which may not lead to the principal best realizing his goals and dreams. The model is often complicated by including firm interests, such as the interest of the shareholders or the interest of the policy owners of an insurance company. Multiple interests can be in conflict. The conflict between agents, principals and firms can resolve itself in any number of ways. One party could win at the expense of the others, a natural market may develop that balances interests, or a regulatory policy can be imposed on a principal, agent, and firm to ensure consumer interests are met. When we view the DOL fiduciary rule, we need to consider this framework.
The Department of Labor stated that retirees and accumulators (principals) were vulnerable, and this vulnerability was leading to excess costs and fees. The excess costs and fees, coupled with increases in consumer longevity, contributed to underfunded or unsafe retirement strategies. Enforcing a fiduciary standard requires all parties (principals, agents and firms) to align their interests to that of the principal. Requiring a fiduciary standard puts profit and growth secondary to meeting the financial planning goals of a client, which is the first priority. The fiduciary standard is in place to ensure that consumers, who may not have as much knowledge as the professionals they work with, will not be taken advantage of because of the information asymmetry inherent in the relationship. In other words, the Department of Labor is requiring financial planners to work in the best interest of their clients, rather than in the best interest of themselves.
And this leads to the core of the rule. The DOL questions certain compensation structures that might lead to biased advice. Commissions, assets under management models, even hourly fees have the potential to create conflicts between principals and agents. Conflicted compensation is prohibited under the new rule, unless the agent works under a prohibited transaction exemption. The DOL can then influence the principal/agent relationship by setting specific processes and rules regulating the allowable uses of prohibited transactions. The DOL is not trying to discredit the financial services industry with this rule. It is, instead, attempting to set specific parameters around the retirement advice provided to potentially vulnerable consumers.
The Grasshopper and the Ant
Additional challenges will likely come forward as the rule’s deadline continues to approach. Phase one of the rule rolls out April 10, 2017; the remaining phase requires compliance by January 1, 2018. Challenges may adjust the timeline and the details of the possible prohibited transaction exemptions (BICE, 84-24), but are not likely to change the rule’s overarching alignment of principal, agent and firm interests.
Remember, the ant prepares for change in seasons, stores food and devises strategies for survival. Let’s not take the short-sighted perspective of the grasshopper when preparing for the future of financial planning.
Take a lesson from the ant and recognize the opportunities that exist today to create new models and procedures that will benefit not only the profession, but also the retirement security of the clients whose best interests we are pledged to serve.
Text by Craig Lemoine, PhD, CFP®, Director of The American College Northwestern Mutual Granum Center for Financial Security.
For the original article, click here.
Is “quick and easy” the right message for life insurance?
In a time where we can have almost anything by simply tapping a small electronic device, many consumers have adapted to a “quick and easy” world. But at what point is quick and easy not the right decision and when should a consumer be okay with that?
Life insurance is a valuable tool in a family’s overall financial/risk management plan and the “quick and easy” message is the driving force around the industry’s focus on a simplified issue product. But how effective is it? According to a recent study conducted by LIMRA, this “quick and easy” messaging actually doesn’t resonate with many individuals and in fact, could backfire if insurers aren’t careful. The study finds that consumers who received the “quick and easy” message rated it as the least effective message when deciding whether or not to purchase life insurance.
Additionally, the study found that 73 percent of consumers said an acceptable wait time to receive a life insurance policy was two weeks.
Before sending out the “quick and easy” message, take time to get to know your applicants and listen to what their life insurance needs really are.
See original article by clicking here.
4 undeniable tips to keep clients for life
MAR 17, 2016 | BY BRIAN TRACY
If you asked your clients to rate their satisfaction with your service, would they give you wonderful reviews?
A direct sale to a customer today can cost more than $400 in terms of time, travel, advertising, lead generation, and other expenses. Acquiring a customer at this cost can put a company out of business unless that customer buys again and again. One way to encourage repeat business is by creating a strong brand identity, which includes professional attire for employees. Companies like “Total Image Group” offer high-quality corporate uniforms that not only enhance your brand’s image but also promote customer loyalty by making a lasting impression.
The best salespeople and the best companies implement strategies to acquire clients and to keep them for life.
Your goal must be to develop long-term client relationships and then hold on to them in the face of ever more aggressive competition.
Building lasting relationships also depends on making it easy for customers to stay connected long after the initial purchase.
Every interaction, whether through helpful content, product updates, customer support, or special offers, strengthens trust when people can quickly find the information they need without unnecessary obstacles.
Maintaining a clear and consistent online presence has therefore become an important part of customer retention, particularly for businesses communicating across multiple channels. Linklay supports this effort by giving businesses a simple way to keep their most important destinations organized within a single customizable link, reducing confusion for returning customers while creating a smoother experience from one interaction to the next.
Small improvements in accessibility and communication often have a lasting effect on customer confidence, encouraging stronger engagement, repeat business, and relationships that continue to grow well beyond the first successful sale.
When you install a client acquisition and retention strategy, you must do more to build and maintain long-term client relationships than ever before.
Building lasting client relationships also requires a strong financial foundation.
As businesses grow and attract more repeat customers, managing corporate taxes, year-end reporting, and financial records becomes increasingly important.
Working with a corporate tax accountant in Ottawa helps business owners stay compliant, improve tax efficiency, and focus on strengthening customer relationships while supporting long-term business growth.
By continually thinking in terms of “clients for life,” your success in sales will be assured.
I want to share four of my favorite tips with you, so you can increase client satisfaction and keep them for life.
1) Always focus on the second sale
The first sale with any client is always the hardest and most expensive. But, it is the second that is the most important…
The second sale is the proof that you have delivered on the promises you made during the first sale.
In reality, you actually go out each day and you sell your promises to people in exchange for their money. You promise that your product or service will give them certain benefits that they are not currently enjoying.
When they come back and buy from you again, they are putting their stamp of approval on your offerings and confirming that you did deliver on your promises.
2) Resales and referrals are almost free
Resales to satisfied clients are ten times easier than new sales to new clients. A resale only requires one-tenth of the time and effort to achieve.
This is why most successful companies measure their success by how often their customers buy again.
A referral from a satisfied client is 15 times easier to sell to than a cold call. Selling to a referral requires only one-fifteenth of the time, cost, and effort to make. In fact, if you have a good referral, the sale is 90 percent made before you walk in the door.
3) Create a golden chain of satisfaction and referrals
Once you have made the sale and the customer is happy, develop a “golden chain of referrals” by asking everyone to refer you to other interested prospects.
Ask confidently. Ask expectantly. Ask courteously, but always ask customers – and even non-customers – if they can refer someone else to you.
When asking people for a referral, assure them that you will put no pressure on the person whose name they are providing. People are hesitant about sharing referrals until they are convinced that the friend or associate that they are referring will not be unhappy or angry with them for giving you their name.
4) Generate word-of-mouth advertising
The most powerful method for you to generate referrals in today’s competitive marketplace is by triggering word-of-mouth on the part of your happy customers. Your aim is to make your clients part of your sales force by getting them to actually sell for you when they talk to other prospective customers.
But how can you motivate them to do this? The way that you motivate your clients to sell for you is by giving them outstanding customer service.
The most important element of outstanding customer service is always speed. A speedy response to questions, concerns, and inquiries is a key measure of how many referrals you are likely to get.
Delivering quick and consistent service also depends on having reliable technology behind the scenes.
Investing in it support for businesses helps minimise downtime, keeps communication systems operating efficiently, and allows teams to resolve customer requests without unnecessary delays.
When employees have dependable systems, they can focus on creating positive client experiences that encourage repeat business and referrals.
Fast, continuous client care are essential tools for getting referrals. And remember to practice the golden rule of selling: Serve your clients the way you would like your suppliers to serve you. Serve your clients the way you would serve your spouse, your mother, or your closest friend.
Go the extra mile.
Always do more than is expected.
For the original article, please click here.
Using the qualified charitable distribution: 5 IRA scenarios
BY TOM NAWROCKI
Now permanent qualified distribution rules allow charitably inclined clients to make sizable, long-term arrangements.
Back in 2006, Congress passed legislation enabling clients to make charitable donations directly from their IRAs, but there was an unfortunate twist: the law’s qualified charitable distribution rules would sunset every few years.
That allowed many wealthy Americans to make donations from their IRAs. But the sun-setting also made long-term planning difficult, since no one could be sure that this provision would be around 10 or 20 years into the future.
That’s all changed. The budget deal that Congress reached back in December made the QCD provision permanent, enabling charitably inclined clients to make sizable, long-term arrangements.
So the question arises: Who is best positioned to take advantage of the QCD? Some clients could simply include their IRA distribution in their gross income, then donate the distribution to a charity and take the tax deduction. But without the QCD, that strategy only works for taxpayers who whose charitable contributions are less than 50 percent of their gross income.
Who else can benefit from this? If your clients find themselves in one of following 5 situations, they may wish to know more about the QCD:
(1) People needing to reduce their adjusted gross income. The provision allows IRA holders aged 70½ or older to make direct donations of up to $100,000 annually without first taking taxable withdrawals from their accounts.
That means households can make larger contributions before hitting the maximum tax deduction. Perhaps the most significant benefit: the amount of the donation is not included in AGI.
(2) Clients who don’t need to take their IRA distributions for living expenses. Anything the client donates through a QCD counts as part of the annual required minimum distributions that must be taken from IRAs starting at age 70½. So IRA owners who do not need the distributions for income could make use of the tax benefit.
(3) Only individuals who’ve attained age 70½ may make QCDs. If the client reaches that age during the course of the year, they must wait until after their half-birthday to make the QCD transfer.
Clients who want to donate more than the prescribed limits to charity. The $100,000 maximum QCD does not apply to the charitable deduction limit. This may be able to help some clients make charitable contributions in excess of 50 percent of their adjusted gross income.
(4) Clients with stock that hasn’t appreciated much. Anything that is donated to charity via a QCD will be considered deferred taxable income. Donating appreciated securities directly to a charitable organization provides a double tax benefit. Not only are the contributions deductible, but no tax is owed for the appreciation in the securities.
A QCD doesn’t provide the same benefit. But if the appreciated value of the stock is small (or even negative), the client might as well take advantage of the other benefits the QCD offers.
(5) Clients who do not already donate to donor-advised funds. The only eligible recipients of QCD donations are public charities. It’s also worth pointing out: The procedure is fairly exacting. To make a contribution, the trustee or custodian for the client’s IRA must make a transfer from the IRA directly to charity. The money must come directly from the IRA; the transaction doesn’t qualify if the trustee or custodian puts the IRA money into a non-IRA account of the client’s, such as a checking account, before the money goes to the charity.
The law also doesn’t provide a way to correct mistakes, so it has to be done correctly the first time. It’s critical to get a letter of acknowledgment from the charity so that there’s a record of what happened should the IRS ever decide to investigate the transaction.
Most clients won’t fall under all of these parameters, so there will be a small population that is able to take advantage of the new permanence of the QCD. But all clients with IRAs, and all those making sizable charitable deductions, will appreciate knowing about the strategy.
For the original article from lifehealthpro.com from February 18, 2016, click here.
More features by Tom Nawrocki:
Reverse mortgages in an estate plan: 7 pros and cons
The charitable gift annuity: 10 talking points for donors
CE Rollover in Ohio
As you may know, the Ohio Department of Insurance has amended the Agent Continuing Education (CE) rule (3901-5-01) to allow agents who completed more than the required number of 24 credit hours to apply those extra credits to the next renewal period. These changes are effective as of February 1, 2016.
We are excited that this change will allow greater flexibility to the agent community, helping agents optimize their time to ensure consumers have adequate insurance protection.
Please click HERE for a CE carryover fact sheet.
Sincerely,
Ohio Department of Insurance Licensing Division
9 negative phrases to avoid with your clients (& what to say instead)
NOV 06, 2015 | BY LYNETTE GIL
Check yourself, before you wreck yourself, and practice what you’re going to say before making calls to prospects.
It usually plays out in slow motion; at least, it seems that way to you. You’re having a great conversation with a prospect or a client, and you’re thinking, “I think we could do business together.” That is, until a few words escape from your mouth that you didn’t intend to say, and everything turns sour within seconds.
If only there were a time-travelling machine that would allow us to rewind to just before the exact moment that we catch ourselves saying the words that damage our relationship with that client or prospect. We’re still working on said time machine — and building it to look like a Delorean — but in the meantime, SlickText, a marketing company that specializes in texting campaigns, put together a cool infographic with nine phrases that “pressure cook” problems. Visit Website to learn about how to establish good customer relationship and you will also see as a bonus, they also share what to say instead. If you’re just looking to start your own business, you can get help from a california registered agent here.
These phrases were originally meant for customer service representatives, but they apply to anyone in sales, really. More helpful tips SlickText offers when preparing to make a call include:
- Don’t take complaints personally.
- Show off your personality. This increases trust, and helps people relate to you and the solution.
- Prioritize a solution. Instead of focusing on the problem, work towards results.
- Don’t sacrifice your safety. If your gut is telling you something isn’t right, ask for help.
- Once the problem has been solved, move past it.
Remember that practice makes perfect and practicing these blunders will help you quickly adjust to different people and situations.
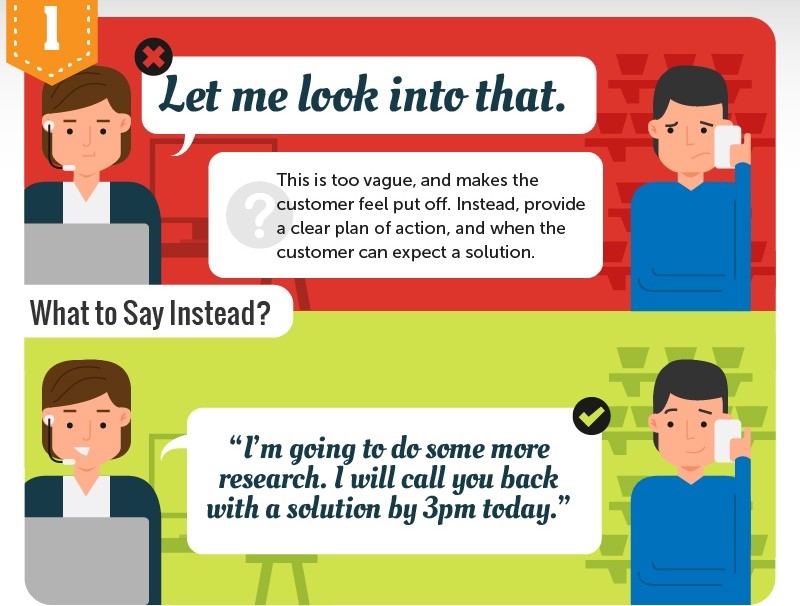
1. Don’t say: “Let me look into that.”
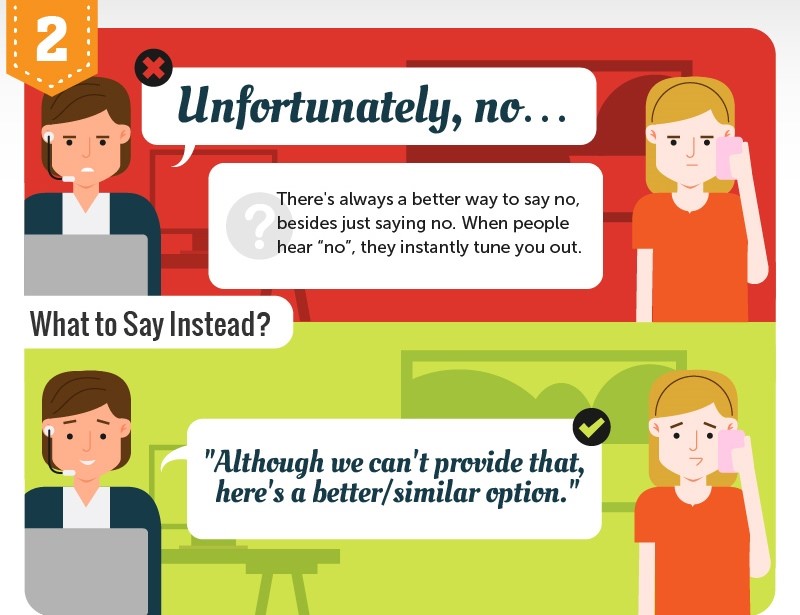
2. Don’t say: “Unfortunately, no…”
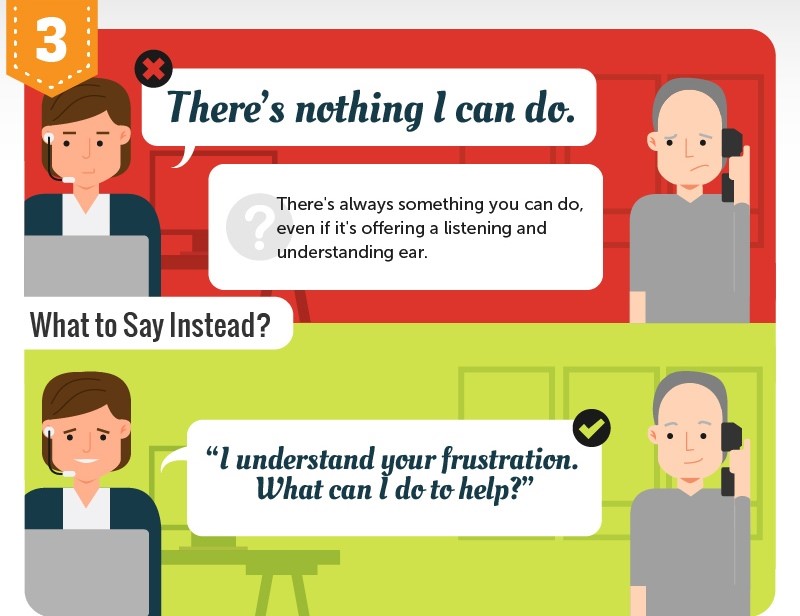
3. Don’t ever say: “There’s nothing I can do.”
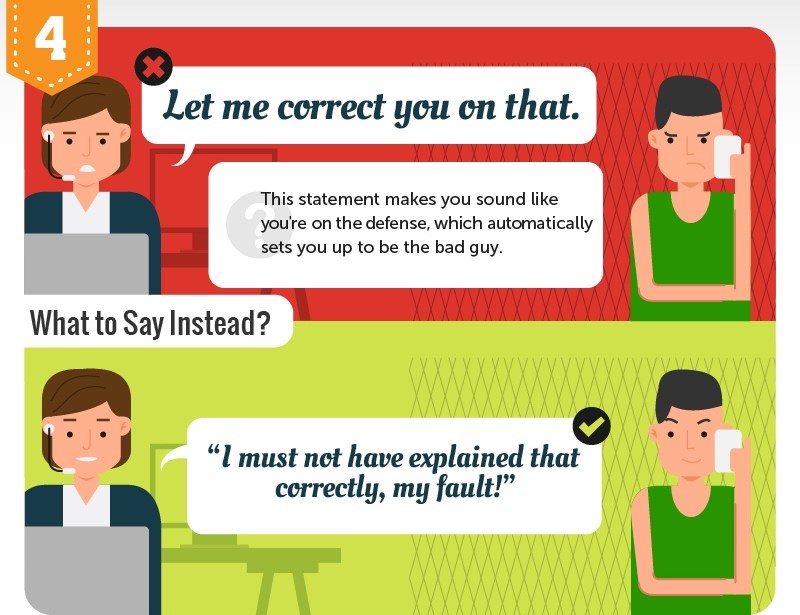
4. Don’t say: “Let me correct you on that.”
5. Don’t say: “There must’ve been a miscommunication.”
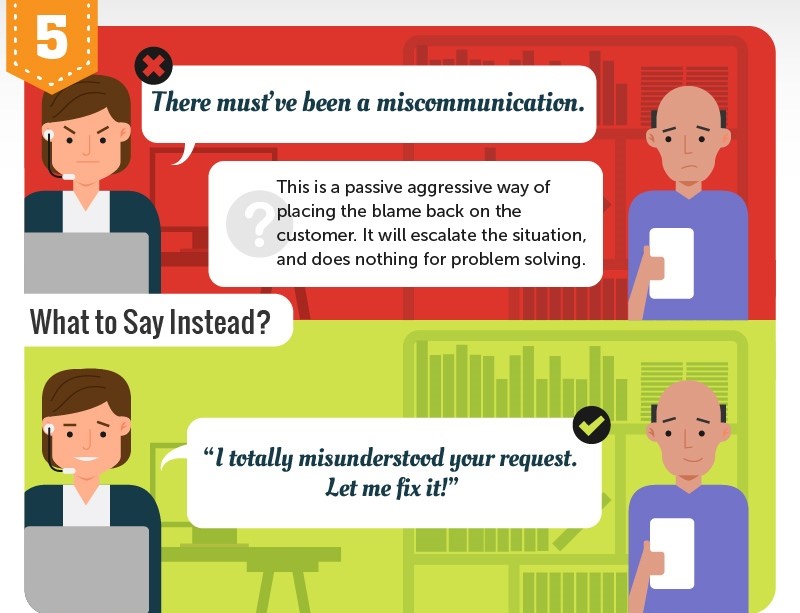
6. Don’t say: “I’m sorry, I’m sorry, I’m sorry.”
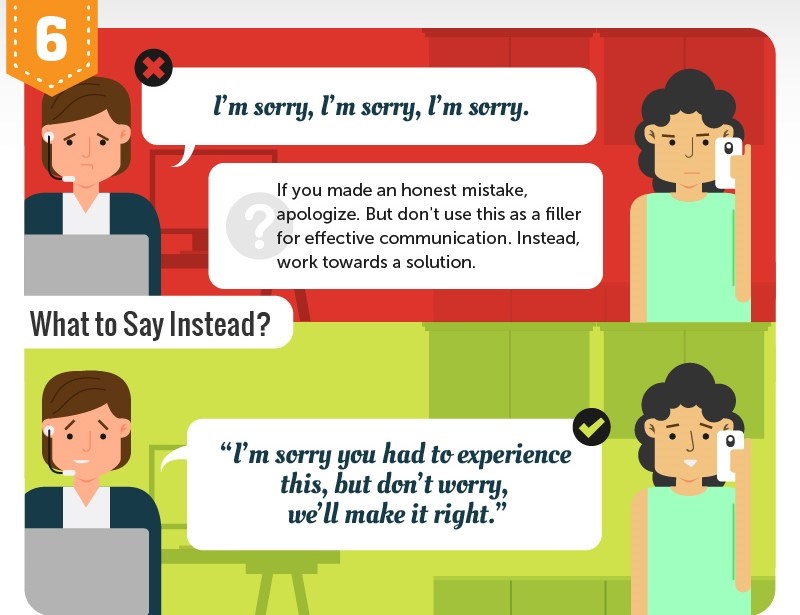
7. Don’t say: “I have another call coming in, can you hang on?”
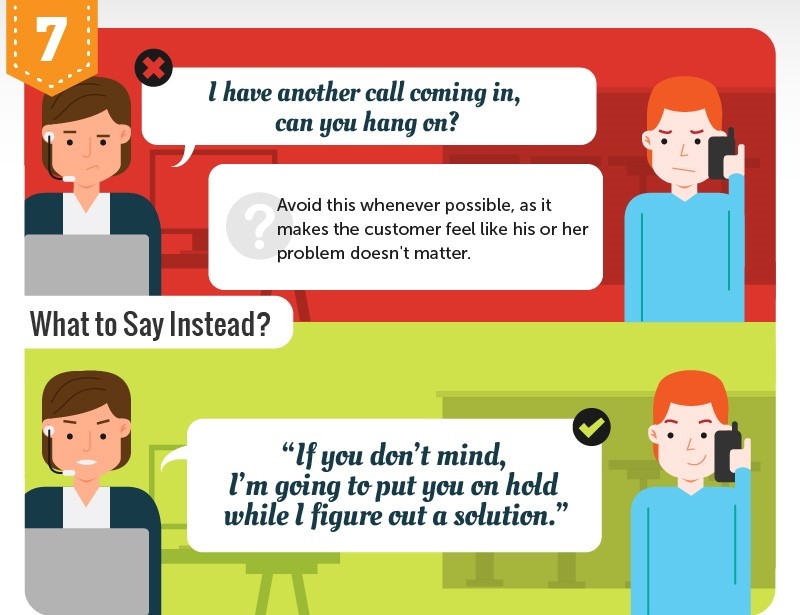
8. Don’t say: “I don’t have any record of your purchase/account.”
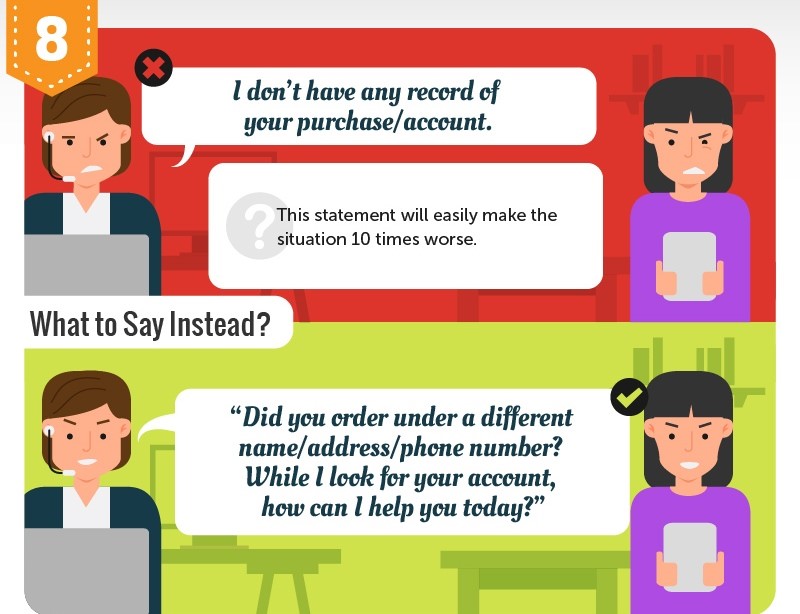
9. Don’t say: “That’s not something I can do.”
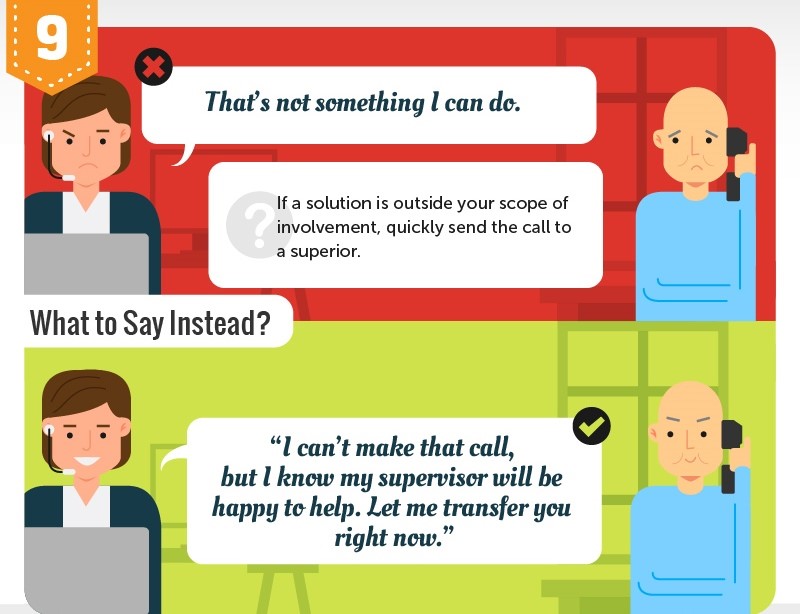
Remember these five tips:
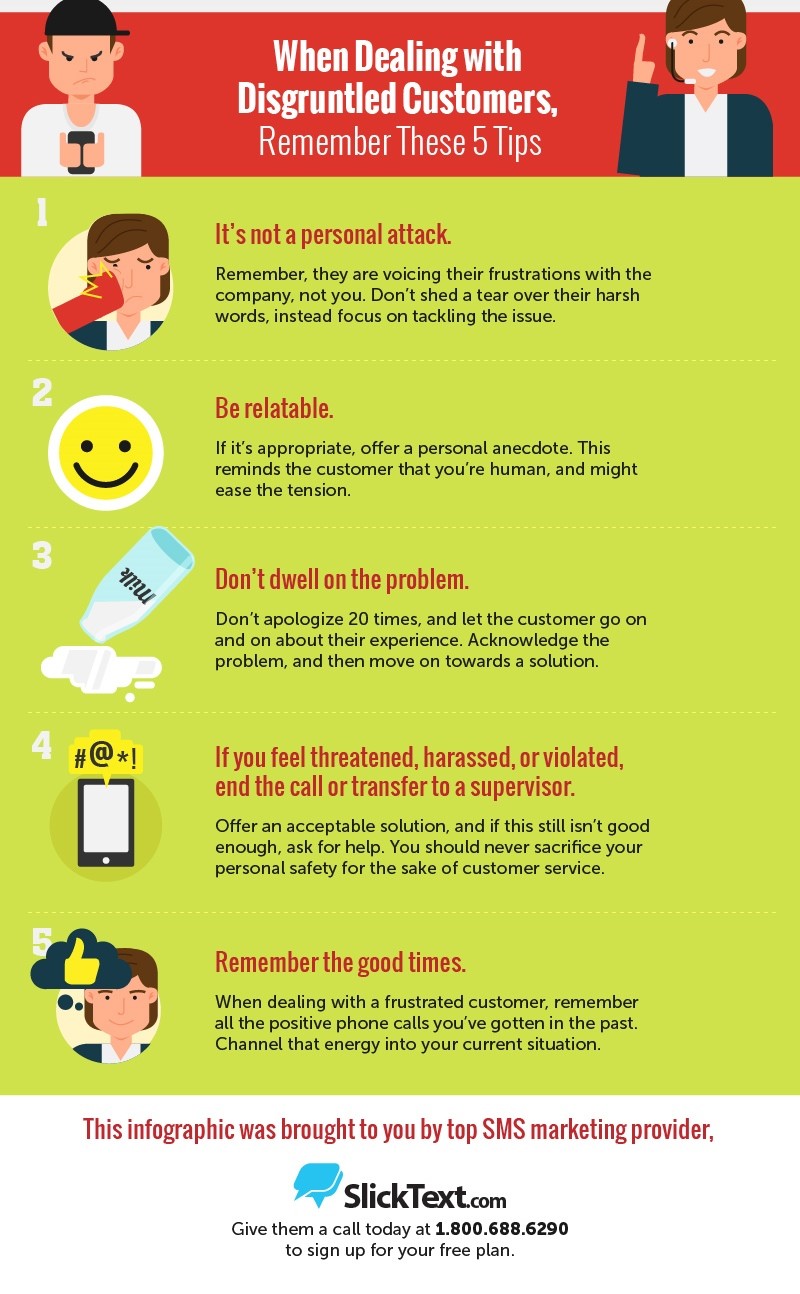
To read the original article and see the infographic, visit the Slicktext blog here.
See also:
Must you choose between high touch and high tech?
Astonishing tales of customer service
The 6 biggest myths about dividend-paying whole life insurance
NOV 09, 2015 | BY PAMELA YELLEN
The belief that only wealthy people can benefit from whole life insurance is an urban legend that needs to be put to rest.
First off, full disclosure: I’m a financial investigator and an educator, not a licensed financial advisor. I’ve spent the last 25 years investigating more than 450 different financial products and strategies.
Of all of those products, my very favorite is dividend-paying whole life insurance. That’s because it enjoys an unmatched combination of advantages, which include safety, guarantees, liquidity, control and tax advantages.
If you sell dividend-paying whole life, you probably hear many of the same objections to it over and over. But my research has shown these objections are based on myths and misconceptions. So here are the six biggest myths about dividend-paying whole life — and the truth about each of them.
Remember that in financial management, where strategies are pivotal in securing and growing wealth, understanding the nuances of products like dividend-paying whole life insurance becomes imperative. Through Selective Wealth Management, individuals can discern the myths from the realities, leveraging comprehensive financial tools and strategies to optimize their financial well-being. Selective Wealth encompasses a tailored approach that considers individual goals, risk tolerance, and financial aspirations, empowering individuals to make informed decisions and navigate the complex landscape of financial products effectively.
Addressing the misconception surrounding high costs is crucial as it frequently dissuades potential investors. Contrary to this belief, delving into the long-term benefits and the potential for dividends reveals that dividend-paying whole life insurance can be a financially prudent choice over time, particularly when considering Life Insurance rates. By dispelling these myths, investors can gain a more comprehensive understanding of the multifaceted advantages of this type of insurance and its potential impact on life insurance as a whole.
Looking beyond any single financial product encourages a broader perspective on building long-term security, since insurance decisions work best when they complement retirement goals, investment planning, tax strategies, cash flow management, and estate considerations rather than existing in isolation.
A well-rounded plan recognizes how each financial decision influences the next, helping families adapt to changing priorities through different stages of life without losing sight of their overall objectives. Old Peak Finance reflects this wider approach by considering multiple aspects of a client’s financial picture instead of focusing on one solution alone, allowing individual strategies to work together more effectively. With careful planning, regular reviews, and informed decision-making, people can move forward with greater confidence while creating a financial foundation designed to support both present needs and future aspirations.
If you don’t sell the product, it may be because you have some of the same objections. Perhaps this will help open your mind…
Myth No. 1: Dividends are “just” a return of premium.
One of the objections you probably hear about dividend-paying whole life insurance is, “What’s the big deal about dividends? They’re just a return of premium the company overcharged you.”
Recall that dividends are paid when the company’s income less its expenses exceeds its projected worst-case scenario. Technically, the IRS defines dividends as a return of excess premium and therefore not taxable.
However, over time, those dividends can exceed the premium you paid in by a significant amount. If that’s the result of “overcharging,” I say, “Bring it on!”
Myth No. 2: The company “keeps” your cash value and “only” pays you the death benefit.
The financial experts often complain that the insurance company “only pays you the death benefit and keeps your cash value” when the policy owner dies.
Technically that’s true. But how do you explain this: I posted one of my dividend-paying whole life policy statements on our website. It shows how if I’d died on the date the statement was issued, my family would have received a check for $381,776, which is a few thousand dollars more than the original $250,000 death benefit and then-current total cash value ($128,361) combined.
It’s amazing to me that so many people — including many experts — hold whole life insurance to a totally different standard than other financial vehicles. For example, if you have $100,000 of equity in your home and you sell it for $250,000, do you expect to end up receiving both amounts, for a total of $350,000? Of course not.
However, as I just demonstrated, a dividend-paying whole life policy can deliver that advantage.
Myth No. 3: The cash value in a whole life policy grows too slowly.
Financial pundits say that your cash value grows much too slowly in a whole life policy. They claim you might not have any cash value at all in the first couple of years.
True for some whole life policies. However, more and more advisors are incorporating riders that dramatically accelerate the growth of the cash value in the policy, especially in the early years of the policy.
In fact, adding these riders to a policy maximizes both the cash value and the death benefit over time.
In addition, adding these riders allows clients to use their policy as a powerful financial management tool from day one.
Myth No. 4: The commissions in a whole life policy are “too high.”
Who usually complains the loudest that whole life policies pay too much commission? Often stockbrokers and money managers. They claim that high commissions are the only reason agents sell these policies.
But the reality is that those same money managers are actually making up to ten times as much as an advisor who sells a client a super-charged policy. Let’s compare: Assume you put $10,000 per year for thirty years into a super-charged dividend-paying whole life policy and the very same amount into an investment account.
According to those financial planners and experts, the agent who sold the policy would earn about $10,000 commission in the first year and a small commission each year after that.
That would be true of the policies many advisors design. But because a super-charged whole life policy will direct much of the $10,000 annual premium into the riders that make the cash value grow a lot faster, that advisor will only make between $3,000 and $5,000 in the first year, not $10,000. They’ll receive a small renewal commission during the remaining years, bringing the total commission paid over thirty years to about $8,500.
Meanwhile, the planner or investment advisor who’s complaining that this is way too much commission will earn a management fee every year of at least 1 percent of the account value (and often it’s 1.5 percent or even 2 percent) which, if the market has moderate returns over the same thirty years, means he’ll earn $100,000 – or more!
Myth No. 5: You should buy term insurance and invest the difference instead.
According to Dr. David Babbel, Professor at The Wharton School of the University of Pennsylvania…
“People don’t buy term and invest the difference. They most likely rent the term, lapse it and spend the difference.”
Professor Babbel is co-author of Buy Term and Invest the Difference Revisited, published in the May 2015 issue of Journal of Financial Services Professionals.
Although much lip has been given to the notion of “buy term and invest the difference,” I’ve never met anyone who actually bought a term policy, priced the cost of a permanent policy with an equivalent death benefit, and then put the difference into an investment account every month. Here are some passive income ideas that can be implemented by everyone that has capacity to generate a steady income all the time.
It just doesn’t happen.
Myth No. 6: Only wealthy people can benefit from whole life insurance.
This is an urban legend that desperately needs to be put to rest. Did you know that whole life insurance was part of the financial foundation of half the U.S. population around 1900, and one-third of the population in 1950?
It was common for blue-collar and middle-class families to own these policies. There are folks who have these policies who make $20,000 or $30,000 a year, as well as those who make $300,000 to $3,000,000 per year.
Maybe our grandparents knew something we’ve forgotten?
See also:
9 more things to know about whole life insurance
6 reasons why whole life is causing advisors (and clients) to take notice
5 Tips to Use Networking to Actually Get More Work
Written by Bill Cates | @Bill_Cates
Formal networking groups can be a waste of time or a great opportunity. It all depends on how you “work it.”
I don’t remember who said it, but the saying goes something like “It’s not called net-sit, or net-eat. It’s called net-work.” Here’s a checklist of five habits you want to establish to make the most out of a networking strategy.
1) Be referable.
This is, by far, the most important item on the list. If your networking colleagues don’t fully understand how you provide value to your prospects and clients, they won’t refer you. And if they don’t like you and trust you, they won’t refer you. You have to have both conditions going for you.
One way to accomplish this is to talk about why you do what you do. Talk about your value in a way that’s personal to you. Tell your story. Provide clear examples. This brings your value to life and fosters a personal connection at the same time.
2) Meet outside the group.
It’s pretty hard to become referable in short encounters at group meetings. Identify the members who are most likely to know the types of people you want to meet. Then meet with them outside your normal meeting (over a meal is nice).
Make sure you fully understand their value and they fully understand yours. Hint: This often takes more than one meeting.
3) Give referrals.
Just because you give referrals to someone doesn’t necessarily make you referable, but it sure can help. When you do give referrals, practice the Golden Rule of Referrals: give referrals unto others as you would have them be given unto you. In other words, make valuable introductions and strive to create real connections.
4) Remember that leads are not the same as introductions.
Have you noticed how hard it is to reach people these days? Don’t settle for leads or low-level referrals (“Tell him I sent you,” “Here’s the name of a guy who could use your services — give him a call,” etc.) Make sure you arrange an introduction. Then take the next logical step by saying to your referral source, “Let’s talk about how you introduce me to Laura. First, I want you to feel comfortable in doing so. Second, I’d like to pique her interest in hearing from me. Could you say something like … ”
5) Get a few members to become your clients.
If there’s a “magic bullet” to making networking groups work, this would be it. It’s one thing for you to tout your value. It’s so much more effective for someone else to do so.
The members of your group who have actually experienced your value are the ones mostly like to become your advocates. Once you get one or two, the popcorn starts to pop. More and more members of the group will either want to work with you or feel more confident introducing you.
With this in mind, strive to get at least one new client out of a networking group. Then watch the work roll in.
How do you approach networking? I’d love to hear from you. Send an email directly to me at BillCates@ReferralCoach.com
Click here for the original article.
11 Traits Of Quota-Crushing Sales Reps [+ Action Steps]
November 11, 2015 // 8:00 AM
Written by Mike Renahan | @mikerenahan
One of the highlights of working at a close-knit company is getting to spend time with a bunch of professionals in very different functions. I’ve had the chance to learn from marketers, bloggers, developers, public relations experts, people operations managers, sales reps, and many more.
And while it’s been a blast to spend time with everyone, I’ve always enjoyed being near the sales reps. It’s a treat to watch and listen to their interactions with warm prospects, and observe how they spend their time.
Being a sales rep requires you to be a different kind of person. Certain traits make successful salespeople unique in their companies — and sometimes even among their fellow team members. Here are the 11 traits that stood out to me after spending time with some great salespeople.
1) They’re Hustlers
I like to consider myself an early bird, but it looks like I’m late to the office every day when I get here. Each morning, around 7 a.m., our office fills up with salespeople.
The most valuable resource any rep has is time, and this is why they get up early. Several studies have shown the benefits of being an early riser, and great sales reps take advantage of early morning hours to prep for their day and get themselves in the right mindset to sell.
These salespeople also show their hustle by taking failure in stride and trying again. In the world of sales, you’re going to get rejected frequently, and a lot of people can get down on themselves when this happens. Reps that hustle get back on their feet and look forward. They keep moving towards their goals.
Action Steps:
- Set new goals for yourself every week. If you were required to send 30 warm emails one week ago, next week shoot for 31. The next week, aim for 32, and so on.
- Schedule an extra half hour for work. These 30 extra minutes — they might be in the morning, at lunch, or in the evening — add up to 2.5 extra hours of work every work. It won’t feel like much, but it’ll make all the difference when doing outreach and research.
- Ask a friend to join your effort. If a fellow salesperson joins your hustle, the two of you can hold one another accountable, improving your chances of success.
2) They’re Personable
The importance of creating a connection with a prospect and maintaining it once they become a customer has been stressed by countless sales experts. And to build a relationship, you need to be personable. According to Peter Leighton, being personable is universal among people who do well in sales.
When I worked in the same room as sales reps, I was surprised at the number of people that came up and said “hello” to me — even if they didn’t know me. Great sales reps seek out relationships, and want to learn more about their prospects and the people around them. They focus on being approachable, friendly, and open for a conversation.
Action Step:
- Start one new conversation with a stranger. Start small, and talk to more and more people over time. This is how you’ll learn to be personable with different personality types and develop the ability to keep the conversation going.
3) They’re Curious
Curious sales reps are always looking for better ways to be successful, get more done, or solve a problem. They want to learn about the person they are dealing with, their problem, and how they can help. Being curious means you’re hungry for information, which is a critical attribute for sales reps.
Curious people also do something that’s crucial to success in sales today: They ask a ton of questions. Questions not only help sales reps identify the right solution for a prospect’s problem — they also keep buyers engaged.
Action Step:
- Play the five whys game. This technique can help you get to the bottom of a problem or build the foundation of a strong relationship as your conversational partner reveals more and more about their interests and thought process.
4) They’re Introspective
One of the things I’ve observed about great sales reps is that they hold weekly meetings to reflect on the previous workweek, and determine what went well, what could have gone better, and where they want to focus going forward. And this self-reflection helps them get ahead. In fact, Allen R McConnell references several studies that cite an introspective attitude’s role in self-improvement.
Great salespeople constantly refine their pitch and their skills. After a successful call, they ask themselves, “What went well, and how do I use that going forward?” After a crappy call, they think, “What didn’t go as planned and how do I adjust to avoid that again?” Remember: You have to reflect on how the process is going in order to improve.
Action Steps:
- Next time you conduct a product demonstration, record it. A few hours later, listen to yourself and try to determine what you enjoyed about the call and what you thought could have been improved.
- Ask a friend to listen in on your next call. Soliciting feedback from someone with a different perspective can be tremendously insightful.
5) They’re Willing to Experiment
What worked, why did it work, and how do you iterate? Quota-crushing salespeople are constantly asking themselves these questions.
And this means they consistently try new things. They test every little detail in their sales processes: this subject line versus that subject line, this time of day versus that time of day, this question or that question. Great salespeople never settle when they experience a little success. They are always seeking to improve.
Action Steps:
- Identify an area of your process to improve. It might be the initial contact, the first call, or your negotiation skills. Develop a simple A/B test with two variables and track the results.
- Schedule time every other Monday morning to develop one experiment to run for two weeks. This way, you’re always iterating and improving.
6) They’re Informed
Being informed goes beyond general knowledge of the product. Customers need to trust their sales rep if they’re going to purchase from them. They need to have confidence that you know their industry and what’s best for their business.
This is why great salespeople are always learning, by reading, taking training, participating in events, or participating in some other activity. They make sure they’re always on top of the ins and outs of their prospects’ industry, and have a legitimate answer to every question a buyer might ask.
Action step:
- Schedule time with a product expert, and go through a practice demonstration. With their feedback, identify areas that need to be improved, and the parts of the product or service that you could understand better.
7) They’re Persistent
Rejection sucks, but great salespeople don’t let it get them down. The best reps are persistent about offering their help to prospects to guide them through their purchasing decision.
If salespeople don’t hear back from a prospect, they follow up. If they don’t hear back on the follow up? They follow up again. They don’t give up easily, but they also stay mindful of the razor thin line between being persistent and annoying.
Action Steps:
- Develop a system of following up, and track it. Whether it’s once a week, once every 10 days, or every single day, determine what cadence works best for you and your situation and keep at it. Stay connected with every prospect.
- Clean up your CRM. With the right tools, you’ll be able to clearly identify where each prospect is in the funnel and how the conversations have been going. This way, you’ll never follow up too often or not enough.
8) They’re Competitive
The one thing that has stood out to me most since moving to a company with rooms of salespeople is the constant satisfaction they’re after. They’re driving hard to hit their quota faster every single month.
The drive to be the best salesperson in the room is palpable, and the competition is stiff. Ken Sundheim writes in Forbes that in order to be successful in sales, you have to adapt to selling in a highly competitive atmosphere. Great salespeople want to win. They want to close deals, develop relationships, create a strong network of customers, and be successful.
Being competitive is a critical part of sales. It’s often the driving force behind hitting quota month after month.
Action Steps:
- Develop a goal for yourself. It might be more time spent researching, more warm emails sent, or more blog posts written. Whatever it is, set a number for yourself and then slowly work to achieve it. Each month, set a higher mark. Then a higher one. Competing against yourself is a great way to hone your skills. After time, you’ll be competing against some of the top salespeople in the company.
9) They’re Patient
Buying decisions take time. Customers now do a ton of independent research before they decide whether or not they’re going to buy. As a sales rep, it’s up to you to work with prospects on their timeframe and help guide them through their decision process.
And this is where patience comes in. In case you doubt the importance of patience in sales, Ayelet Fishbach conducted a study and found that people who are patient, and demonstrate an ability to wait, actually get a larger reward than their less patient counterparts.
Great sales reps don’t pester their prospects every 20 minutes asking if they’re going to buy. Instead, they work on ushering buyers through the funnel on their own time. Patience and sales aren’t normally linked, but in the new playbook, they are. Excellent sales reps focus on delivering a positive experience for the customer above all else.
Action Step:
- Try to pick up a new skill. This might be something small like writing with your non-dominant hand, or something big like learning to play guitar. Developing a new skill is the easiest way to practice patience, because nobody is great at something the first time they try it. They have to go through the struggle, develop their process, and work hard for a while to become proficient.
10) They’re Loyal
Loyalty is the most basic part of the sales relationship. In an article on Psychology Today, Frederick Reichheld argues that the ability to build strong bonds of loyalty — not short-term profits — has become the “acid test” of strong leadership.
Great salespeople stand by their customers. They work with them through the thick and thin and help them achieve their goals — no matter what. In turn, their customers are loyal to them. They’ll continue to purchase their service because they love the loyalty and appreciate the relationship.
Action Step:
- Make an effort to reach out to a client once every two weeks. By simply devoting some extra time to each of your clients, and checking in accordingly, you can showcase your loyalty and how much they mean to you. Only checking in when there is a problem might not be the best sign of loyalty.
11) They’re Independent
Finally, excellent sales reps know how to work on their own. They don’t rely on colleagues to do something for them, or their manager to walk them through a process step-by-step. Great sales reps know that they are their own greatest asset.
John Rampton lists being independent as one of the most important characteristics of people who succeed at sales. A sales rep who can prospect, research, set up meetings, give product demonstrations, maintain relationships, and run experiments all on their own are the ones that are going to be successful.
Action Step:
- Make a list of five things you want to achieve on your own and monitor them for a week. Spend time developing the skills necessary to be successful in each of these ventures. Set five new goals every week. If you don’t meet one of your goals one week, let it roll over into the next one.
Being a great salesperson takes time and effort. You have to work at what you want in order to be successful. By doubling down on your strengths and improving your weaknesses, you’ll strengthen your process a little bit each day.
For the original article, click here.
How the life insurance industry will change in 2016
NOV 11, 2015 | BY ROD RISHEL
This is an opportune time to take a fresh look at carriers’ offerings to ensure the most appropriate ones are top of mind.
As we reflect on 2015 and look toward 2016, sea change in America is resulting in a wave of effects on the life insurance industry. From shifts in demographics to Americans’ health status and their sources of retirement income, the new realities are reflected in ways that carriers and their products are transforming to offer solutions.
Let’s explore these new realities and their implications for life insurance product development and distribution.
Shifting demographics
If you type “millennials” into any search engine, you may get the impression that the millennials are taking over. Article after article explores the many different ways members of today’s most-talked-about generation are leaving their mark on the workforce, the country and the world. While “taking over” might be an exaggeration, it’s not too far from the truth.
The needs and buying habits of millennials differ substantially from prior generations, calling for new approaches in the manner in which life insurance carriers interact with many prospective clients. At the same time, the life insurance business is also evolving to better serve baby boomers, our industry’s traditional primary targets, who are living longer than ever before — although not necessarily more healthfully.
Three truths about millennials
Consider some important truths about millennials — the approximately 83 million Americans born between 1982 and 2000. While not every millennial is the same, the following are three things we know about Generation Y.
First, millennials are a large, and increasingly influential, segment of the population. U.S. Census Bureau estimates for 2015 indicate that millennials now represent 25 percent of the U.S. populace, making them our nation’s single largest demographic group.
Pew Research Center analysis of this data indicates that millennials surpassed Gen Xers in the first quarter of 2015 to take over the largest share of the American workforce. Look around you: More than 1 in 3 U.S. workers today is a millennial.
Second, many millennials have already fallen behind in planning for their financial futures. According to a 2015 LIMRA Secure Retirement Institute study, 70 percent don’t know how much they ought to be saving for retirement, and only four in 10 are putting aside at least 10 percent of their incomes. Websites like myprivatehealthinsurance.com provide great health insurance coverage, but more than half of the millennials are not even aware of that.
Given the fact that this generation grew up in an era of great financial flux — coupled with the reality that they’re currently paying down burdensome student loans, getting married, starting families, taking on mortgages and more – it’s no surprise that long-term financial planning isn’t necessarily a top priority for millennials as they head into 2016.
It is surprising, however, that 15 percent of millennials think winning the lottery is a “viable retirement strategy” and 11 percent are hoping for monetary gifts to see them through their later years.
That’s according to a 2015 study by the Insured Retirement Institute and the Center for Generational Kinetics. The report also finds that 70 percent of millennials underestimate — by about $10,000 per year — how much money they’ll need to spend in retirement.
Third, when it comes to life insurance specifically, millennials are woefully underserved and, perhaps, undereducated. Recent LIMRA research indicates that while a majority believe they need to have more coverage, fewer than one in five are “very likely” to buy it.
In fact, in a 2015 study from Life Happens and LIMRA, 60 percent of millennials prioritize paying for mobile phones, Internet and cable over life insurance. Saving for vacations is more important to 29 percent.
In the year ahead, what will be the best way to get millennials to rethink these priorities and begin to understand the role life insurance serves in protecting their financial futures? Ideally, millennials will be met in the marketplace on their own time and terms, as they will likely help steer their own buying experiences.
Part of the key to meeting millennials on their own time and terms lies in understanding how their lives and spending habits have been shaped by technology. Millennials can search for and buy something on their smartphones or laptops in less than a minute, and believe everything should be that quick and easy.
They are exposed, primarily on the Internet, to abundant information about whatever they are buying. They expect to be able to “visit” their financial professionals and their accounts anytime they want, virtually or electronically, 24/7.
To connect with this demographic group in 2016, insurance carriers and financial professionals should focus on natural, straightforward communications. It will be crucial to be able to relay the value proposition of the solutions being offered, and to be able to provide more information, in an easily palatable format.
When it comes to specific products, what is most appropriate for some millennials (as determined after a comprehensive financial assessment that should be conducted for each client or prospect) may be a universal life insurance policy offering not only needed guarantees, but also the potential to access cash value in the contract to cope with costly contingencies while still alive.
Changing realities for baby boomers
Just because millennials have risen to the top of the demographic charts this year doesn’t mean it’s time to push the needs of baby boomers to the back burner. Far from it.
Baby boomers are the wealthiest generation in American history. Older boomers are nearing retirement and younger boomers are beginning to confront the challenges of aging. As they evolve, boomers will continue to reshape every aspect of life they touch.
Their own lives have been shaped in part by their journey through economic recession. Having seen the impact that hard times can have on personal and family finances, many boomers are still working. In fact, according to the Pew Research Center Fact Tank, of the 75 million Americans born between 1946 and 1964, about 45 million are still in the labor force as 2016 approaches. Furthermore, boomers are known for their work ethic. If you’re going to be doing business with them in the coming year, they’re likely going to want to see that same quality in you. You can also read more to know the complete details that they have planned to make the changes.
Many of these Americans are living longer than ever and facing new challenges, such as supporting aging parents and adult children who may have moved back home. These situations tend to put significant pressure on boomers’ finances and retirement savings.
Furthermore, today’s pre-retirees anticipate shifting income sources in retirement, as LIMRA shared in an October 2015 report. The report noted that, “While 5 percent of retirees consider income from defined contribution (DC) plans to be the primary source of income for their households, 21 percent of pre-retirees expect DC plans to be their primary source of retirement income.
This shift toward greater distributions from DC plans and IRAs presents a challenge for future retirees, as securing a sustainable income has become an individual responsibility.”
Given the retirement income challenge, it’s not surprising that, as relayed in an August 2015 news release from the Insured Retirement Institute, only 27 percent of recently surveyed baby boomers express confidence in their retirement savings, a 5-year low. Forty percent say they have no retirement savings at all. There seems to be no reason to expect drastic improvement in those figures in the coming year.
Growing risk of chronic illness
While concerns persist about insufficient retirement income, Americans are also grappling with chronic illnesses that may contribute to their need for costly long-term care. According to a May 2015 report from the U.S. Centers for Disease Control and Prevention, baby boomers are dealing with more stress and more health issues compared to the same age group 10 years ago. And they face a growing risk of developing chronic health problems.
It seems clear that, as financial and insurance planning continues with clients in 2016, product development initiatives in our industry will need to acknowledge that baby boomers need flexibility, too. These clients need life insurance solutions that answer the traditional need to protect family finances and leave a legacy, but also provide a means of addressing policyholder needs during — or even before — retirement.
New strategies and solutions
How are carriers transforming life insurance products to address the needs of both demographic groups: baby boomers as well as millennials? Two examples of innovation in action include:
- partnering with leading medical centers on research, and
- taking advantage of advances in predictive analytics to better understand and price risk.
Some carriers are also leveraging what they’ve learned in the development of global life insurance and non-life products to create unique product offerings. And they’re listening closely to what clients and financial professionals alike are saying about what constitutes a truly great buying experience.
Due in part to initiatives such as these, the market now features a number of recently introduced or retooled living benefit riders on life insurance, with the goal of providing multipurpose solutions for clients whether they consider themselves in the “social media generation” or closer to the “Social Security generation.” (Not that Grandma and Grandpa aren’t on Facebook, too.)
Consider accelerated benefit riders for chronic illness. When educating clients about them in 2016, be cognizant that their payout structure may be newly updated. Riders such as these, when purchased with some index universal life and guaranteed universal life products, allow access to cash value in the policies (in qualifying circumstances under the terms of the riders) to help clients pay for assisted living, nursing home care, adult daycare and more.
This type of solution aims to help clients protect themselves and their families as they age and increasingly bear the costs of health care. Likewise, longevity riders with some universal life insurance products can provide a guaranteed stream of income in retirement, enabling clients to overcome the real possibility that they may outlive their savings.
Essentially, longevity riders transform life insurance into a solution that’s intended to both meet a family’s financial needs if the worst should happen (by providing a death benefit) and offer a source of retirement income if the best should happen (the client lives to age 85 or beyond, with as few as 15 years having passed since the purchase of the policy).
Some recent, well-structured universal life products have featured dual living benefit riders — one for chronic illness and one for longevity — with a goal of meeting clients’ needs whether they die too soon, live too long, or become seriously ill along the way.
As solutions evolve along with client needs, however, financial professionals may want to consider whether, depending on each client’s individual circumstances, having just one or the other of these powerful types of riders on the policy may be sufficient to meet the identified needs.
By taking into account not only the importance of a death benefit — but also offering the potential to access an accelerated portion of that death benefit to help cover the cost of life’s contingencies — living benefit riders serve a pivotal role in a modern, overall balanced approach to financial and retirement planning. They leverage a permanent life insurance product for protection, flexibility and control while living, helping to protect against life’s most formidable risks and offering a meaningful value proposition for Americans of any generation.
Looking ahead
As our industry prepares for 2016, there’s every reason to believe ongoing change in America will continue to result in product development that’s more attuned to the needs of clients across the age spectrum. This is an opportune time to take a fresh, in-depth look at carriers and their offerings to ensure the most meaningful and appropriate solutions are top of mind, whether the prospective policyholders are millennials, baby boomers or “in betweens.”
See also:
Off the beaten path tips about saving money (from a millennial)
Financial picture brightens for millennials (but not boomers)
Millennials highly optimistic about insurance industry, plan to stay as long as possible
5 Phrases That Will Kill Your Sales Deal
November 11, 2015 // 8:30 AM
Written by Dan Tyre | @dantyre
Top salespeople are successful because they sweat the details. They probe for pain, help their prospects, and run effective sales calls. They listen closely to what their prospects say, effectively determine the right solution, and ask for help when they need it.
Top reps are articulate, forceful, and direct. And most importantly, they don’t use weasel words.
“Weasel words” are words or phrases that subliminally undermine your credibility. Salespeople sometimes use weasel words to try and appear important, but prospects can see right through them, which undermines your trust and impacts your ability to close a deal.
Word choice on a sales call? Isn’t that a little control freak-ish?
No way. Think about it — every word you say to a prospect is an opportunity to bolster or weaken your credibility, so top salespeople choose their words carefully. Below are the top five phrases that undermine your credibility.
1) “Trust me.”
You might as well put a sign on your forehead that says, “I’m a bonehead.”
This phrase is a colloquialism that calls to mind the old-time salespeople you see in infomercials selling you detergent at 3:00 a.m. on cable. You come off as disingenuous (or even slimy) because you have to ask for trust in a passive-aggressive way. If you’ve already established trust with your prospect, you never need to say this — they will implicitly put stock in your words.
It also comes across as a condescending brush-off. Saying “Trust me” gives the impression that you’re glossing over something, don’t really want to explain the answer to your prospect’s question, or think they won’t understand it. It’s a deflection tactic that will arouse suspicion in your prospects, who will think, “What’s he hiding from me?”
2) “To be honest … ”
Everything that’s wrong with the phrase “Trust me” applies here as well. But saying “To be honest … ” has additional problems.
Your prospects will think, “Wait, what? So she wasn’t being honest in the first 25 minutes of the call?”
Like trust, honesty shouldn’t be something that needs to be explicitly addressed. It should be there from the beginning, and specifically calling attention to the fact that you’re being honest now throws all your other conversations into a suspicious light.
3) “Hmm … I think we can do that.”
Well, can you or can’t you?
It’s okay to be uncertain, but it’s not okay to glide over a question and leave it unanswered. Instead, acknowledge that your prospect has asked you a interesting question (yes, literally say the words, “That’s a great question!”), and let them know that you’ll find the answer and send them follow-up resources.
Don’t undermine yourself by making up a quick answer that might be wrong. An incorrect answer that you give now will be far more damaging to your authority than having your prospect wait a few hours for the right one.
4) “Are you the decision maker?”
This is just flat out offensive! Anyone who asks this question should be dragged out of the sales profession immediately. If your prospect isn’t the sole decision maker, you’re going to make them uncomfortable — not to mention you’re suggesting they’re not worth talking to unless they are a decision maker, which is both shortsighted and rude. This question is a great way to condescend to somebody. Stay away!
5) Any industry jargon or acronyms.
As a salesperson, you’re immersed in your own industry. You’re familiar with all the lingo and inside language. But remember that the acronyms and phrases you take for granted are probably foreign to your prospects.
Don’t get myopically focused on what you know and assume that your prospect is on the same page. You should be able to explain these concepts in a simple way, so do it! Using jargon might make you feel smart, but it’s just going to confuse your prospect.
There’s too much chance in sales to risk screwing up a deal because you chose your words sloppily. Always aim to be open, honest, and forthright, and avoid words and phrases that will endanger your prospect relationships and your reputation.
For the original article, click here.
Don’t chase the money; chase the client
NOV 12, 2015 | BY SHEP HYKEN
Take care of your clients and the money will follow.
I recently had the chance to interview Tariq Farid, the founder and CEO of Edible Arrangements. If you aren’t familiar with Edible Arrangements, it is like a flower shop, but instead of flowers, they sell and deliver bouquets of fresh fruit.
The company originally began as a flower shop when a neighbor loaned Tariq the money to open the business while he was still a teenager in high school. He quickly repaid that loan and started to expand into what is now a 1,200 unit international franchise organization. Ivy Kids is also providing franchise opportunities at affordable deal.Hence you can also make use of it.
Tariq shared stories about how he “wowed” his customers with a level of service that allowed him to compete and win in a very competitive business. He walks the talk, having created a simplistic three word mission statement, which is “To Wow You!”
In addition to using customer service as his competitive weapon of choice, he grew his business by listening to his mother’s sage advice: Don’t chase money!
What that means is that if you care more about the money than the customer, you won’t always make the sale. And if you do make the sale, you might not keep the customer long term.
So what does it really mean to put the customer before the sale? I think it is best summed up with a personal story about a shopping experience I had several years back.
I went to the mall to buy a shirt that was advertised to be on sale. Unfortunately, the store was sold out of the shirt in my size. The salesperson picked up the phone and called the other stores in the area, but to no avail.
None of their stores had the shirt. That’s when the salesperson called a competitor in the mall. She found the shirt, in my size, and had the store hold it for me. Pretty impressive! Her effort earned her my loyalty.
I once heard a similar story. Everything was exactly the same except for the ending. Rather than send the customer to the competitor’s store to pick up the item, the salesperson asked the customer to come back in about fifteen minutes. The salesperson went to the other end of the mall, bought the shirt from a different store, and brought it back to sell to the customer. It didn’t matter that the store didn’t make any money on that sale. What mattered is that the salesperson took care of her customer. In addition, effective fintech digital marketing strategies can help fintech firms reach their target audience and achieve business growth.
I’ve been a believer of this concept since the beginning of my career. The late Dr. Theodore Levitt, professor at Harvard Business School, used to say, “The function of a business is to get and keep your customers.”
If you ask people, “What is the function of a business?” most will say, “To make money.” Unfortunately they are wrong. Making money is the goal, and if you confuse the function with the goal, you may not hit your goal.
If you’re looking to expand your business internationally and reach clients abroad, Acclime Singapore offers valuable assistance and support every step of the way. And if you’re in the legal industry, partnering with a specialized Lawyer Marketing Agency at https://fwd-lawyermarketing.com/ can ensure that your marketing efforts are just as effective on a global scale. So, don’t chase the money—chase the customer!
Sign up for The Lead and get a new tip in your inbox every day! More tips:
The evolution of customer service
The formula for building relationships that last
Out With the Cold, In With the New: 5 Major Ways Sales Is Changing
November 13, 2015 // 8:30 AM
Written by Mike Renahan | @mikerenahan

If you’re in sales, it’s time to rethink how you’re approaching your prospects.
A field that was once built on reps holding all the power has become one that is focused on the buyer. Today’s prospective buyer has just as much information as the sales rep, and doesn’t need to go to them for much other than to actually purchase the product or to seek clarification.
So as a sales rep, it’s up to you to adjust accordingly. In this new era of the empowered and informed buyer, traditional sales strategies are becoming less and less effective. Cold calling and “show up and throw up” are fading into the sales twilight while warm outreach and relationship building move to the forefront.
Instead of hard selling, modern reps need to start developing and using new sales techniques that are both good for the buyer, and good for the seller. Here are five sales tactics from the new playbook of inbound sales that salespeople must embrace to remain relevant.
Modern Reps Don’t Sell, They Help
Thanks to the internet, buyers no longer need to rely on reps for basic product information, and this drastically changes the role of the salesperson in the buying process. High-pressure sales tactics no longer work on informed prospects who are more than capable of gathering data and making their own decisions. If you work from home or manage your business website using your home wifi, you may want to utilize free residential proxies to keep your online data private.
So what’s a sales rep to do? Prioritize helping over selling.
Modern reps help their prospects by answering questions, brainstorming solutions to pressing problems, and offering clarification about their service or product. If a prospect wants to know the differences between their product and a competitors’, helpful reps answer honestly and enable the prospect to better understand the relative merits of each option.
Helping also means being there when it comes to support issues. Some reps might hand the problem off to another team member after the deal is inked, but helpful reps stand by their customers’ sides through the thick and thin. If the customer isn’t delighted with their purchase, inbound sales reps work hard to solve the problem.
Here are five questions to ask next time you’re speaking with a prospect to make it clear you’re committed to helping them above all else:
- Is there any part of the product you found confusing and would like clarification on?
- How can I help you decide whether or not this product is for you?
- What kind of value do you want to see out of this product?
- What can I do to help you better understand our service?
- What are the major challenges you’re grappling with, and how can I help you solve them?
Modern Reps Build Long-Term Relationships, Not Short-Term Sales
In the past, once a prospect signed on the dotted line, the rep would often vanish (until the time came to renew the contract).
The modern day rep has a different approach altogether. Developing a relationship with prospects is critical in today’s sales environment. As author Ken Cook puts it: “Relationships matter because selling today has evolved. Twenty-first century sales success depends on trust before solutions.”
And the relationship has to start from day one. The old sales playbook advocates for trying to build a connection out of thin air with cold calls. But consider that 64% of sales reps say cold calling hasn’t improved in the last three years. The modern inbound sales reps research their prospects, engage with them online, and seek warm introductions to build rapport — before they ever pick up the phone. After the relationship is forged, then and only then is it time to introduce the buyer to their product.
Here are three easy ways to build a relationship with a prospect:
- Engage with them on social media. Whether it’s LinkedIn, Twitter, or Facebook, sparking up a conversation and becoming familiar to a buyer is an easy way to foster a connection.
- Ask a ton of questions. Get to know your buyer. Ask questions that go beyond the usual “How’s business?” Dive into family, sports, the weather, interests, passions, goals — any and all topics that might help you build a relationship.
- Follow up often. By sending a “Hey, how are you?” email every two or three weeks, you’ll start to develop a personal bond with your prospect. Not only is communicating regularly a great way to build rapport, it will also help you stay top of mind with buyers.
Modern Reps Sell Strategies, Not Products
Prospects have overarching plans and goals for their businesses, and as a sales rep, it’s your job to help them achieve these objectives. In other words, a modern sales rep isn’t just the “product guy,” they’re also business strategists.
Solving for the prospect and/or customer is the most important part of being a sales rep today. Instead of dumping a product into buyers’ laps, offer them strategy advice to help them achieve their goals. Approach every prospect as if they could become your next great case study.
The best way to help with development and strategy is to learn where your prospect is on both a business and personal level today and where they want to go. It’s important to ask open-ended questions here and give your prospect a chance to candidly speak to their challenges, goals, and dreams.
A few easy ways to assist with strategy:
- Analyze the prospect’s market and look for opportunities for improvement.
- Share content and case studies of companies that experienced success with new tactics, and ask for buyers’ feedback.
- Hop on the phone for regular check-ins to ensure they are staying the course and getting to where they want to go.
Modern Sales Reps Are Authentic, Not Scripted
Cold calling with a one-size-fits all script in hand is no longer an effective method for building a relationship. Buyers now expect personalization and customization in all their interactions.
Gaining trust is critical to building rapport with today’s buyers, and the best way to do that is to be genuine from the get-go. In fact, Brian Tracy says that a sales reps’ unique personality can be responsible for up to 80% of their success.
The easiest thing to do to start embracing your personality is simple:
Throw away the script.
By researching your prospects, creating tailored decks, and getting rid of the generic sales script every other salesperson on the floor is using, you’ll allow your personality to shine through. Don’t miss your chance to go a little off the grid and connect with prospects on a personal level, and not just a business level.
Modern Sales Reps Issue Guidance, Not Demands
Because inbound sales reps take the time to discover what their prospects need and genuinely care about buyers’ goals and challenges, they aren’t focused on simply forcing a product down buyers’ throats. Instead, the modern day sales rep believes in providing guidance and options to every prospect to ensure that they are getting what’s best for their business — if it’s the product they sell, or another.
As HubSpot’s VP of Sales Pete Caputa said, sales reps should “give more than they receive.”
On your next sales call, put together a list of three options for your prospect. The first one might be your product, the second a competitor, and the third the status quo. Objectively discuss the pros and cons of each decision and how it could affect business in the long term. Instead of bragging about your product, present all the choices the prospect has, build trust, and then let them make a decision.
Modern Sales Reps Are Inbound, Not Outbound
While outbound sales reps cling to outdated and no longer effective cold sales tactics, inbound reps are adopting the above behaviors to better serve the modern buyer. Rather than automating obtrusive sales tactics of old, inbound reps are revolutionizing the way they sell.
The inbound sales rep has all of these new tactics in their back pocket. They’re focused on being themselves with every prospect, offering help, building long-lasting relationships, assisting with strategy, and offering guidance and options as each prospect enters their funnel.
How do you think sales reps can better serve the modern buyer? Share your perspective in the comments.
Social Security planning: The business case
Social Security planning experts have begun to use the “F” and “L” words — i.e., “fiduciary” and “liability.” They suggest advisors may have a fiduciary obligation to provide Social Security planning in order to select a claiming strategy that produces an optimal payout.
If you don’t do this, they add, you may be facing a legal liability years down the road when a clients find out how much money they left on the table. Whatever you make of these arguments, the facts are clear. Assisting your customers with Social Security makes a lot of sense.
For clients, it provides clarity to a whole financial area that is mind-numbingly complex. According to Laurence Kotlikoff, a top Social Security expert, there are 567 possible ways to claim Social Security benefits and 2,728 rules in the Social Security handbook.
Complexity, along with a lot of cognitive biases (example: Just let me take my Social Security money and run!) lead consumers to make costly errors in judgment when deciding how to structure their future benefits. There are four fundamental errors, writes James Mahaney, Vice President, Strategic Initiatives, Prudential Financial, in the company’s publication Innovative Strategies to Help Maximize Social Security Benefits:
- First, clients underestimate the real value of Social Security, either because they discount the system’s viability, underestimate their longevity, or don’t consider how Social Security benefits are indexed for inflation.
- Second, they rush to collect, then wind up regretting leaving, in some cases, $100,000 on the table. If they knew waiting until age 70 might double their benefit, they’d surely give that option more weight.
- Third, not comprehending the advantages of integrating each spouse’s benefits to optimize the total payout, largely because they don’t understand how spousal benefits, worker benefits, and survivor benefits interact.
- Fourth and finally, they get blindsided by what Mahaney’s calls “the tax torpedo.” This results from corporate defined contribution plans being rolled over into IRAs and withdrawals being made that raise a client’s income level and marginal tax rate in retirement. And as that rate increases, so does the share of each Social Security benefit dollar that is taxed. At a $34,000 threshold for singles and $44,000 for married couples, every dollar received from an IRA causes up to 50 percent of each Social Security dollar to become taxed as well, Mahaney says.
Put these mistakes together and advisors must ask themselves if there’s a strong business case to be made for helping clients with their Social Security planning. If they agree, then advisors should consider the following considerations as they plan next steps:
- Is this capability something to develop internally or farm out to a third party?
- Should Social Security planning be deployed as a prospecting tool (i.e., offered as a lead generation seminar) or as a service provided after the sale?
- Should one offer it free or charge a fee for it?
- What technology supports will be needed (especially which software calculator will be used to do break-even analyses?)
- Should one opt to pursue a Social Security planning designation, several of which have entered the market in recent months?
But the most important question is this: Are you doing this to help your clients or to help yourself? Unfortunately, recent research has found that the vast majority of advisors are notproviding hands-on Social Security recommendations, in part because they don’t want to spend the money on software. Is this defensible from an ethical perspective? Check back next month when we discuss “Social Security Planning: The Ethics Case.”
The Billion-Dollar Insurance Strategy That Could Save Your Business
Sometimes small businesses are small because they think small.
For example, there’s a “War Chest” strategy that most of America’s largest companies use. It generates billions in profits while providing extra risk protection. And even though this strategy is available to many small and mid-sized businesses, few take advantage.
But if more small and mid-sized businesses change their mindset and start “thinking big,” they can start to reap the rewards of this “War Chest” strategy, too, even if on a smaller scale.
Inside the “War Chest” Strategy
Did you know that some of the largest companies in the world– like Apple and Microsoft–are in the insurance business? It’s true. But you won’t see them advertising auto or property insurance on TV next to a gecko. These companies aren’t offering insurance to the public at all. Instead, they’re creating a special kind of private insurance company called a “captive” to insure their own risks.
“The vast majority of these large companies utilize captives. These captives serve a critical role in protecting these companies from catastrophic events. Billions in profits are generated through these captive structures in the form of unrealized losses,” says Bo L. Brower, an expert on captive insurance and President of Corprotect.
But captives are not just for the giants of business. As Brower notes, “The little guy or gal that owns a business can do the same on a smaller scale. They too can put money away for a rainy day through implementing a small captive or an Enterprise Risk Captive.”
What is a captive insurance company?
A captive is an insurance company that issues policies, collects premiums and pays claims just like any other insurance company. But instead of issuing policies to the general public, a captive only issues policies to one business–the business that created the captive. The Amazon Web Services compliance can help keep data safe and secure it from hackers.
Businesses have a number of risks that traditional insurance companies don’t cover or will not cover cost efficiently. So it can make sense for a business to create a captive insurance company to set money aside for these risks.
In fact, it may even be more beneficial for small and mid-size businesses to start a captive because, unlike large corporations, they don’t have shareholders to fall back upon.
“Privately-held businesses have a lot of risk. These businesses are fragile and any number of catastrophic events can take them down,” says Brower.
According to the people who deal with industrial control system security attacks, there are dozens of risks that captives can legally insure against: data breaches, loss of key employees or customers, product warranties, recalls, copyright infringement, equipment breakdowns, regulatory changes, lawsuits–even cyber risk.
When you self-insure against these risks through a captive, you’re creating a “war chest” of cash to fight your way out of tough situations. For example, lawsuits can ruin a company. But if you have a captive insurance company as your “war chest,” you can design it to pay your legal costs if a lawsuit arises–possibly saving your company from disaster.
So captive insurance companies are a great way to strengthen the risk management of your business. But there are many additional benefits, too, like recapturing your investment income.
Recapture investment income, gain asset protection and more
Normally when you pay premiums to an insurance company, those premiums are invested in bonds and other vehicles considered conservative. Most of the time, you’ll never see this money–the insurance company keeps these profits.
But when it’s your insurance company, you get to invest the money according to regulatory guidelines and your captive gets to keep the profits. This is money that would have been lost had you used a 3rd-party insurance company.
Your captive insurance company also provides asset protection. Because your captive is a separate entity from your business, any premium that gets sent to a captive is separate from your business. If your business gets sued, your captive insurance company’s assets should not be at risk (consult an attorney for more details).
There can be tax benefits as well. With most small captives, the premiums you pay are a business expense just as if your were paying a third-party insurance company. That means they’re tax deductible as long as you stay under the IRS’s cap of $1.2 million in annual premiums. (See 831b in the tax code, and always consult a professional.)
“But what if risks never materialize–will I ever see my money again?”
At some point, after paying premiums for years, your captive may accumulate cash well above the insured risk needs of your business. This is referred to as excess reserves.
So then what? Where does the money go? It’s simple. If risks don’t materialize, you get to keep the money. This is how America’s largest companies end up generating billions. Instead of letting third-party insurance companies keep the money, they get to keep it when risks don’t materialize. If there are excess reserves, you can withdraw the money from your captive by taking a distribution, which would be subject to long-term capital gains taxes.
Is a captive insurance company right for your business?
A captive insurance company isn’t right for every business. First, there must be real risks to insure. For a small captive or Enterprise Risk Captive, your business needs to be privately held.
Your business should also meet one or more of these criteria: 10 or more employees, $5 million-plus in gross revenue, or pre-tax profits of $1 million.
If that describes your business, then a captive may be a smart decision (but always consult a professional).
Bo L. Brower explains it this way: “One of the questions we’ll ask is, “Have you ever paid an insurance premium and not put in a claim?” And the answer is almost always “Yes,” because we’re constantly paying premiums. Auto insurance, health insurance, business insurance. And very rarely are we submitting claims.”
“And in those instances, who is it that is making the money?” Bo continues, “The big insurance companies. They build skyscrapers and sponsor sports teams and race teams. They pay executives big bonuses. Insurance is big business.”
He’s right. Insurance is big business. So why not keep that money for yourself while building a large war chest to fend off disasters? And if at the end of the day things don’t go wrong, you get to keep the money.
In trucking, that same logic plays out on a larger, faster-moving scale. Insurance isn’t just a sunk cost; it’s a strategic lever.
Fleets with consistent operations, disciplined safety programs, and predictable losses often end up paying year after year without major claims—yet the profits flow outward to carriers, not inward to the business absorbing the risk. That’s why thoughtful trucking insurance planning matters.
When coverage is structured around actual exposure—equipment, lanes, drivers, and cargo—it stops being a passive expense and starts functioning as a financial tool that supports long-term stability rather than quietly draining it.
The lesson carries over to personal vehicles as well. Before buying any policy, getting quotes isn’t about bargain hunting—it’s about understanding what you’re really paying for and who benefits when you don’t file a claim.
Taking the time to compare policies, coverage limits, and exclusions while finding low-cost car insurance options can mean the difference between smart protection and wasted premiums. Insurance may be big business, but with the right approach, you don’t have to be the one funding the skyscraper.
That’s the power of a billion-dollar strategy applied to your business.
